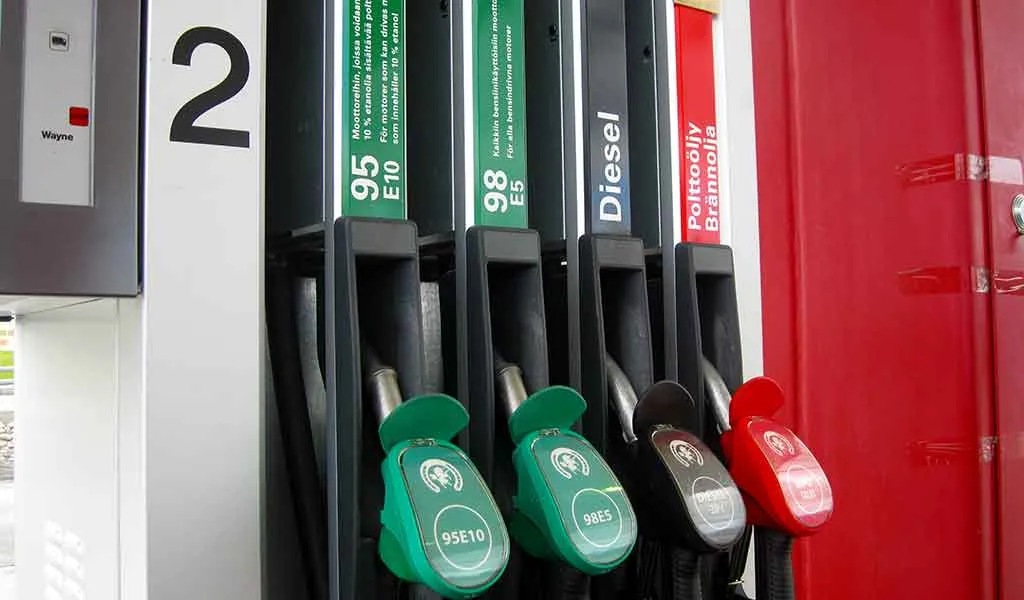
WASHINGTON, United States – US President Donald Trump’s proposed deal to bring Russian diesel into American and global markets is unlikely to deliver significant price relief at the pump, energy analysts say. The announced supplies could add fuel to the market, but they may not resolve the shortages driving prices higher.
The main question is how much diesel will reach buyers, when deliveries will arrive, and where the fuel will ultimately go. Until those details become clear, the agreement remains a supply commitment rather than proof of additional fuel reaching American consumers.
On October 9, Trump said Russia would provide more than 300,000 metric tons of diesel immediately. He also announced further shipments of 500,000 tons in November, followed by 1 million tons and another 3 million tons within a short period.
However, the White House had not provided clear details on who would purchase the fuel, how deliveries would be arranged or when the supplies would become available. Russia’s Deputy Prime Minister Alexander Novak later said Moscow was beginning to lift diesel export restrictions ahead of schedule.
These announcements signal a potential change in supply. Nevertheless, they do not confirm that the announced quantities have been purchased, loaded onto ships, delivered to the United States or sold to consumers.
Diesel Prices Remain High
US diesel prices remained elevated after Trump announced the agreement. The American Automobile Association (AAA) reported a national average of about $6.28 per gallon on October 11, down from roughly $6.34 a week earlier.
The current price remained close to the record high of about $6.53 per gallon recorded on September 22. Although diesel futures fell after Trump announced the deal, that initial market reaction did not translate into an immediate, comparable drop in retail prices.
The distinction matters because futures prices reflect expectations about future supply and demand. Retail prices also depend on wholesale costs, transportation, distribution expenses, taxes and local competition.
Therefore, traders may respond to a supply announcement before fuel reaches a terminal or filling station. Pump prices can take longer to adjust, particularly when wholesale costs remain high.
The US Energy Information Administration (EIA) reported that retail diesel averaged $6.29 per gallon in September. In its October 6 Short-Term Energy Outlook, the agency forecast that prices would remain above $6 in October before gradually declining.
However, the forecast was completed on October 1, before Trump announced the Russian diesel agreement. It therefore reflects the market conditions known at that time, not a measured assessment of the deal’s effects.
Why the Deal May Have Limited Impact
Energy analysts questioned whether the proposed supplies would materially change diesel prices. Clayton Seigle, an energy strategist at the Center for Strategic and International Studies, told the Associated Press that he expected little overall price impact.
Michael Lynch of the Energy Policy Research Foundation offered a similar assessment. He argued that diverting Russian diesel to the United States could leave existing buyers searching for replacement supplies elsewhere.
That creates an important complication. If American buyers receive diesel that would otherwise have gone to another market, the United States could gain supply without increasing the amount available worldwide by the same quantity.
Other buyers would then compete for alternative cargoes. As a result, some of the pressure removed from the US market could reappear in Europe or elsewhere.
The deal could still help particular regions if the fuel arrives where shortages are most severe. However, its effect would depend on delivery locations, timing, transport costs and the availability of competing supplies.
In other words, changing the destination of existing fuel is not necessarily the same as creating a lasting increase in global supply.
The Announced Volumes Need Context
Trump’s announcement described several shipments, beginning with more than 300,000 metric tons and potentially reaching millions of tons over subsequent deliveries.
Those quantities sound substantial. Yet their effect depends on how much reaches the United States and how quickly buyers receive it.
EIA data show that US consumption of distillate fuel oil, a category that includes diesel and heating oil, was about 3.7 million barrels per day in recent weekly figures. This is a broader measure than diesel alone, but it illustrates the scale of the market.
Using a rough conversion of seven to eight barrels per metric ton, an initial shipment of 300,000 tons would equal about 2.1 million to 2.4 million barrels. That is less than one day of US distillate consumption.
The comparison does not mean the shipment would be insignificant. Additional supplies can help a particular port, distributor or region, especially when inventories are tight. However, the announced quantity would not by itself replace the need for sustained production, imports and efficient distribution.
Timing also matters. Fuel must move through the supply chain before it can affect retail prices. Meanwhile, demand continues, and other market disruptions can offset any extra supply.
The full announced volume would have a larger potential effect if delivered as promised. Even so, the public announcement alone does not establish how much fuel will enter the US market or whether all the planned shipments will proceed.
Low Inventories and Refinery Disruptions Add Pressure
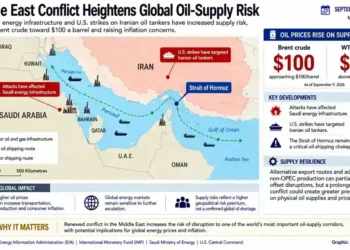
The EIA identified tight inventories and reduced international refinery output as key factors behind high diesel prices.
In its October outlook, the agency reported that East Coast distillate inventories fell 32% below their five-year seasonal average in September. It expected inventories to remain below normal through the coming winter, even as supplies gradually recovered.
Refineries also face pressure from disruptions to crude-oil flows and reduced output in parts of the international market. In addition, seasonal refinery maintenance can limit production just as agricultural demand for diesel rises during the autumn harvest.
These factors affect the market differently from an announced shipment. A cargo can provide a temporary increase in available fuel, but it cannot immediately restore lost refinery capacity or resolve wider shipping problems.
Crude-oil prices also matter, although they are only one part of the final diesel price. Refiners must turn crude into usable products, and the difference between crude-oil costs and wholesale diesel prices can widen when refined fuel becomes scarce.
The EIA said higher crude-oil prices and rising refining margins contributed to September’s retail price increases. It also warned that low inventories could keep diesel prices elevated even as wholesale costs eventually ease.
Consequently, the Russian agreement would enter a market already facing several supply constraints. Its impact would depend on whether the new cargoes can meaningfully offset those pressures.
What the Sanctions Licence Allows
The US Treasury Department’s Office of Foreign Assets Control issued Russia-related General License 135 on October 9. The licence authorizes specified transactions involving the sale, delivery, offloading and importation of Russian-origin diesel.
The authorization runs through 12:01 a.m. Eastern Daylight Time on April 7, 2027. It also contains an explicit restriction involving debits to accounts held by Russia’s central bank, National Wealth Fund and Finance Ministry at US financial institutions.
The licence is a temporary authorization for transactions covered by its terms. It does not amount to a complete or permanent removal of US sanctions against Russia, nor does it establish that every proposed transaction is permitted under all applicable laws.
The measure provides a legal route for covered diesel transactions during the authorization period. However, it does not prove that the fuel has been purchased or that the announced shipments will reach US buyers.
The arrangement also marks a change in policy. Since 2022, the United States had barred Russian energy imports in response to Russia’s invasion of Ukraine. The new licence creates a limited exception for transactions involving Russian-origin diesel.
The distinction between the licence and the supply agreement is important. One establishes what certain transactions may legally do under specified sanctions rules; the other describes the supplies Trump says Russia will provide.
What Russia Could Gain
The arrangement could give Russian suppliers another outlet for diesel stocks and generate revenue from exports. Seigle told the Associated Press that the deal could benefit Russia even if its effect on US prices remained small.
Russian fuel producers have faced disruptions, including Ukrainian attacks on refineries, while Moscow has imposed restrictions on diesel exports to protect domestic supply. Russian officials have said they were lifting some restrictions ahead of schedule.
However, the financial benefit to Russia will depend on the volume actually sold, the prices buyers pay, transport costs and how export proceeds flow through the Russian economy. The public information reviewed for this report does not establish a verified total revenue figure from the agreement.
Nor does the announcement prove that every planned shipment will take place. A reliable assessment will require evidence of completed transactions and deliveries.
The arrangement has also drawn criticism from Ukrainian officials and US lawmakers, who argue that renewed Russian energy sales could undermine pressure on Moscow over the war in Ukraine. Those objections concern the wider policy consequences, separate from whether additional diesel could ease supply conditions in some markets.
Why Consumers May Not See Immediate Relief
Diesel powers much of the freight sector and supports agriculture, construction and other commercial activities. Some homes also use related distillate fuels for heating.
When diesel prices rise, trucking firms and other businesses face higher operating costs. Depending on market conditions, companies may absorb those expenses or pass some of them on through higher charges for transporting goods.
However, the effect on consumer prices is neither automatic nor immediate. It depends on how long fuel costs remain high, how much businesses pay, and whether they can pass the increases on to customers.
The Russian agreement could offer limited relief if new supplies reach areas facing the greatest shortages. Yet a lasting national price decline would likely require broader improvements in inventories, refining output, shipping and crude-oil availability.
The EIA’s October outlook anticipated a gradual decline in retail diesel prices after October, but that forecast preceded the agreement. Future data will be needed to determine whether prices fall faster, remain elevated or move in a different direction.
For now, the central test is delivery. The market needs evidence that the announced fuel has reached buyers and added to available supply, rather than simply changing where existing cargoes are sold.
Until that happens, the agreement offers a possible source of additional diesel, not a guarantee of lower prices for US drivers, farmers or trucking businesses.
Reporting Credit: US Energy Information Administration; US Department of the Treasury, Office of Foreign Assets Control; American Automobile Association; White House.